A serious diagnosis shouldn’t mean financial disaster.
A Critical Illness insurance product pays a lump sum benefit if the insured is diagnosed with one of up to 25 covered conditions and outlives the survival period specified in the contract.
A financial resource for the road back to health.
This product is for people who want a financial resource to help cover additional expenses linked to recovery from a critical illness — time off work, travelling to receive treatment, home care, renovations, and the cost of treatments not covered by public health insurance.
You might already know someone who has benefited from Critical Illness insurance. Or perhaps you have not heard much about it. Either way, in a catastrophic medical emergency such as cancer, leukemia, a heart attack, stroke or a seizure, Critical Illness insurance may be your sole means of avoiding financial disaster.
While a regular life insurance plan covers some needs associated with these conditions, the expenses of surviving a life-threatening illness are often just as significant — and need their own coverage.
Calculate Your Insurance Needs
Coverage depends on your circumstances, the conditions you want protected and the policy wording. A licensed agent can explain exactly what is — and isn’t — covered.
Calculate my needs
Tax-free cash, paid directly to you.
If you are diagnosed with a policy-covered condition, Critical Illness coverage helps you avoid sacrificing savings. The tax-free claim can be used for medication, recovery, a mortgage, rent, or home modifications such as wheelchair accessibility. In fact, the money can be used for anything.
It removes the need to accumulate credit card charges or draw down retirement savings. Funds can go toward non-medical expenses such as transportation and child care, or any other expense that results from illness. The lump sum is paid after the insured has outlived the standard 30-day waiting period.
There are limitations to understand: some variants of cancer may be excluded, and a recurring or repeat condition may not qualify. Policies can also have term limits, such as 10 or 20 years, with a return of premiums possible at the end of the term. Read the policy thoroughly — your Experior agent will help make clear what it does and does not cover, so you are not left wondering in an emergency.
Factors that shape your premium
Cancer risk statistics are frequently cited as one in two Canadians; figures vary by source and age. Ask a licensed agent for current data and what it means for you.
Protection at work, and beyond it.
Critical Illness coverage can be purchased by the policyholder or through the workplace in Canada. Unlike other medical benefits, the cost is usually the employee’s responsibility. The funds can be used for any purpose, including essential medical care that might otherwise have been inaccessible — which is why employers and employees both value these plans.
Medical care beyond Canada's borders
A tax-free claim is paid on diagnosis of a serious illness under a Critical Illness plan, whether treatment happens in Canada or abroad. If you travel outside Canada for medical treatment, the benefit can help cover those costs — and the recovery that follows — without waiting for procedures at home.
Comfort when you need it most
Critical Illness policies provide peace of mind so you can focus on treatment instead of scrambling for cash. Some lower face-amount plans can cost as little as $25 per month — illustrative only; actual rates depend on the plan and insurer. A limited set of illnesses is covered, but generally over 85% of critical illness claims are paid.
A source of income when work stops
A critical illness affects the whole family's financial wellbeing. The lump sum can cover health and home care costs. With a Return of Premium Benefit, premiums you paid may be reimbursed if no claim is made before the term ends — or if you pass away before claiming.
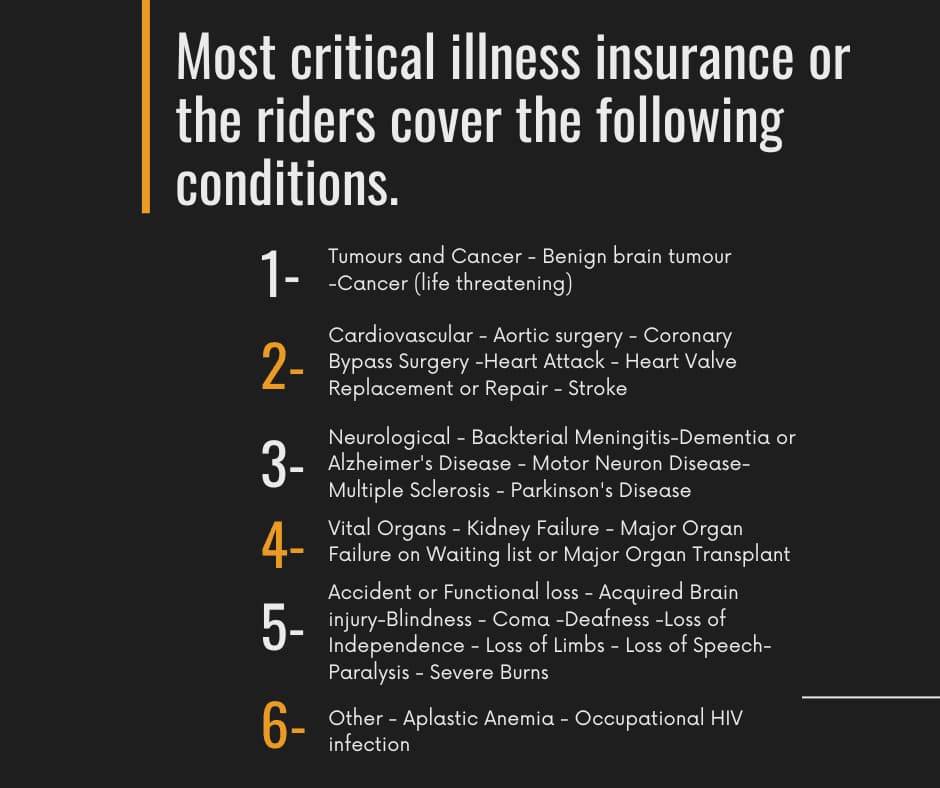
Know the list before you need it.
Most plans cover the illnesses shown below. If you have a pre-existing condition, discuss it with your agent when you review coverage amounts and premiums. Providers and brokers can confirm the exact conditions covered by a specific policy — always ask questions before you buy a quote.
Covered conditions, definitions and exclusions vary by insurer. A licensed Experior agent can walk you through the policy wording in plain language.
A great benefit — with a gap to consider.
Workplace coverage is valuable, but a cushion is wise in case you become unemployed or change careers. Critical Illness insurance pays out as a lump sum, and rates vary — so it is important to speak with a licensed insurance agent who can review the illnesses covered and help you find affordable monthly payments. How much coverage you get is up to you, and having an insurance professional in your corner helps you get the most for your money.
An experienced associate, by your side.
Experior Financial Group understands the importance of comprehensive Critical Illness insurance that protects you during an unforeseen health condition. Our associates know the market and help clients find suitable rates and coverage.
We assign an associate with relevant experience to each client — someone knowledgeable in life, disability and Critical Illness insurance. They will help you determine the best plan for your circumstances at competitive rates.
Plan for recovery, not for the bills.
Book a no-obligation conversation and we’ll review the plans available to you.